Please sign in as a member or guest below to access it.
Please sign in as a member or guest below to access it.

Think before you spend.
An inheritance is a welcome financial boost, but it often comes at an emotionally difficult time. This gift can come in the form of cash, a retirement account, investments, property, or a combination of all the above. Deciphering what you have — and what to do with it — can be overwhelming.
Before making any big moves or plans, get a solid understanding of what you’ve inherited and the financial red tape that may come with it.
The good news is that Texas doesn’t impose an inheritance or estate tax, and federal estate taxes generally only impact large estates. (In 2026, the federal estate and gift tax exemption is $15 million per person.)
Generally, inheritances are not considered taxable income for beneficiaries. But keep in mind: Inherited assets can create taxes later. For example, interest, dividends, or rent payments generated by inherited property may be taxable. Also, selling inherited investments can lead to capital gains or losses.
A monetary inheritance can come in many forms, ranging from cold, hard cash to retirement accounts. Some of the most common forms also include:
Knowing what, exactly, you are inheriting can help you determine the next best steps. Often, a real estate attorney or financial planner can help you make sense of what you’ve inherited and understand any associated rules.
The best course of action is to first define your financial goals. Making this determination can help you decide what to do with the money.
It can be tempting to make plans (and a few daydreams) for your inherited bounty but think before you spend. While there’s no “right” answer for what to do with inherited money, there are a few options to consider that can help it go further.
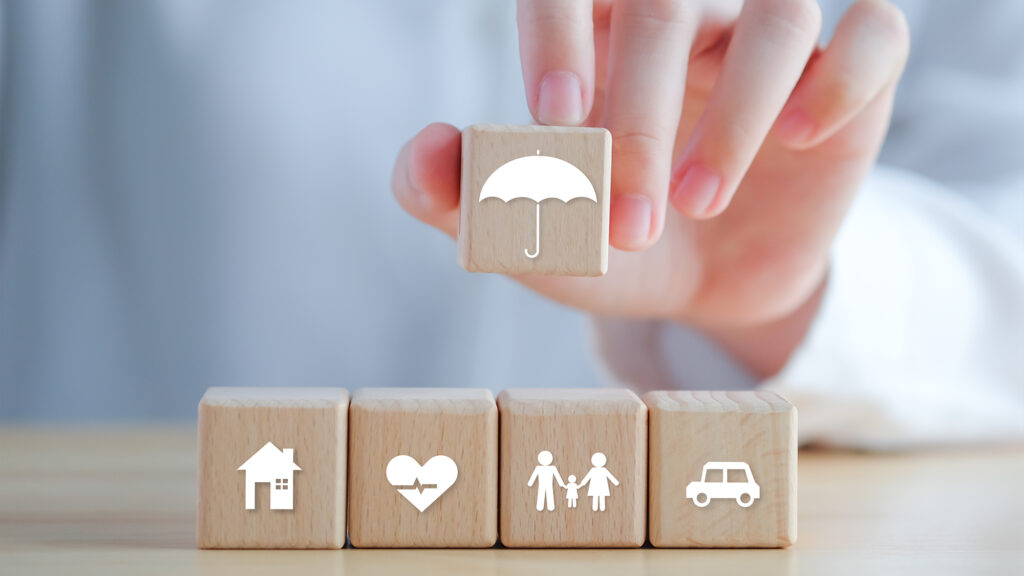
Greater assets can lead to greater liability concerns. If your inheritance has the potential to significantly increase your net worth and assets, you may want to think about investing in an umbrella insurance policy. Typically, umbrella insurance becomes a worthwhile consideration when your net worth, including your home, reaches about $500,000 .
Umbrella insurance can offer an extra layer of protection should your other policies (homeowners, auto, or farm and ranch) become exhausted after an accident. Your Texas Farm Bureau Insurance Agent can walk you through the pros and cons of an umbrella insurance policy to help determine if it’s a good fit for your new needs. Brush up on these umbrella insurance FAQs beforehand.
After navigating the inheritance process, it’s a good time to get your own affairs in order. Take small — but essential — steps such as safely storing important documents and updating your beneficiaries on insurance policies and financial accounts.
If you haven’t already, create a will or update what you currently have on file. Spare your loved ones from navigating Texas’ succession laws should you die without a will in Texas.
As hard as it is to think about, planning ahead is one of the kindest final gifts you can leave loved ones. Take steps to prepare your family for life after loss.
Texas Farm Bureau Member Discounts on Tech
Texas Farm Bureau members save on essential devices and services.

6 Hacks for Managing Your Policy
Save time. And trees.
The Ultimate Holiday Gift Insurance Wish List
Make a list and check it twice.
FAQ: Do You Need Rental Car Insurance?
Don’t make this decision at the counter. First, check your Texas Farm Bureau Insurance auto policy to see if you’re covered.
You’ve got insurance questions. We’ve got answers.
Apps Small-Business Owners Need to Simplify Tax Filing
An app a day might take the pain of taxes away.